

Although Seadrill (currently trading at $47.45 per share) has gained 7.1% over the last six months, it has trailed the S&P 500’s 16.4% return during that period. This might have investors contemplating their next move.
Is there a buying opportunity in Seadrill, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Seadrill Will Underperform?
We don’t have much confidence in Seadrill. Here are three reasons why SDRL doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Shows Momentum
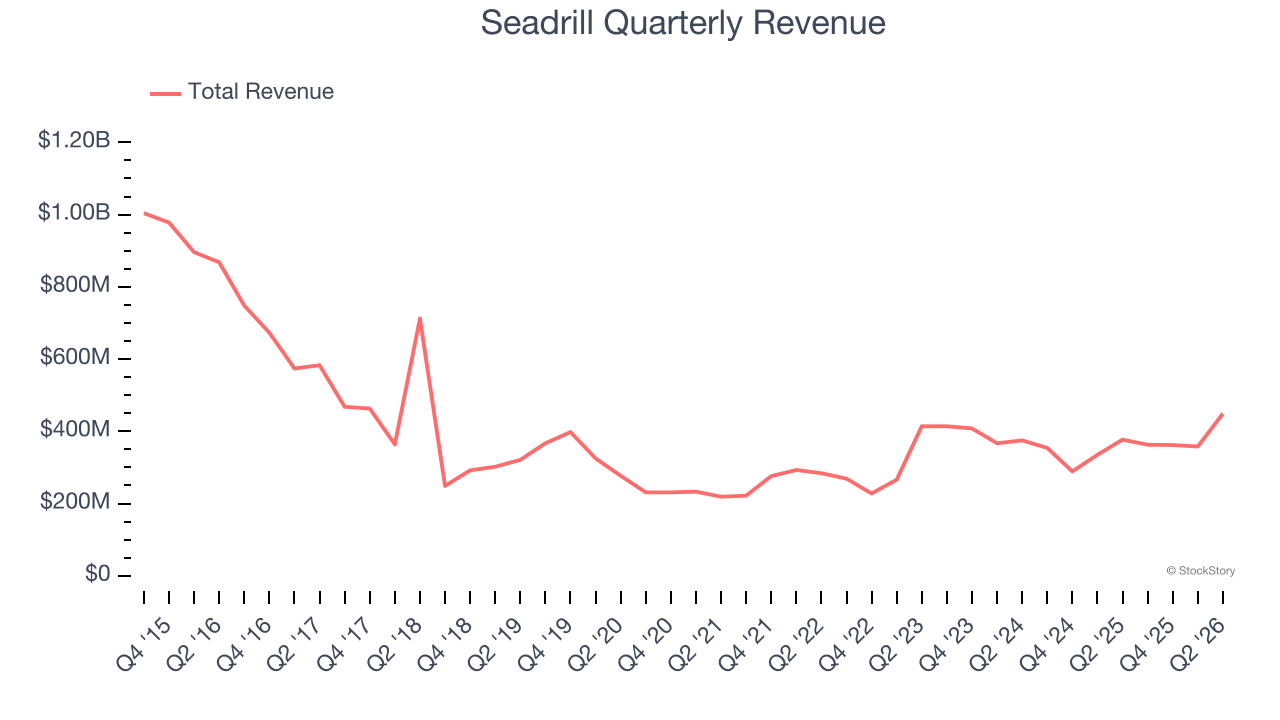
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Over the last five years, Seadrill grew its sales at a decent 10.9% compounded annual growth rate. Its growth was slightly above the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. Low Gross Margin Reveals Weak Structural Profitability
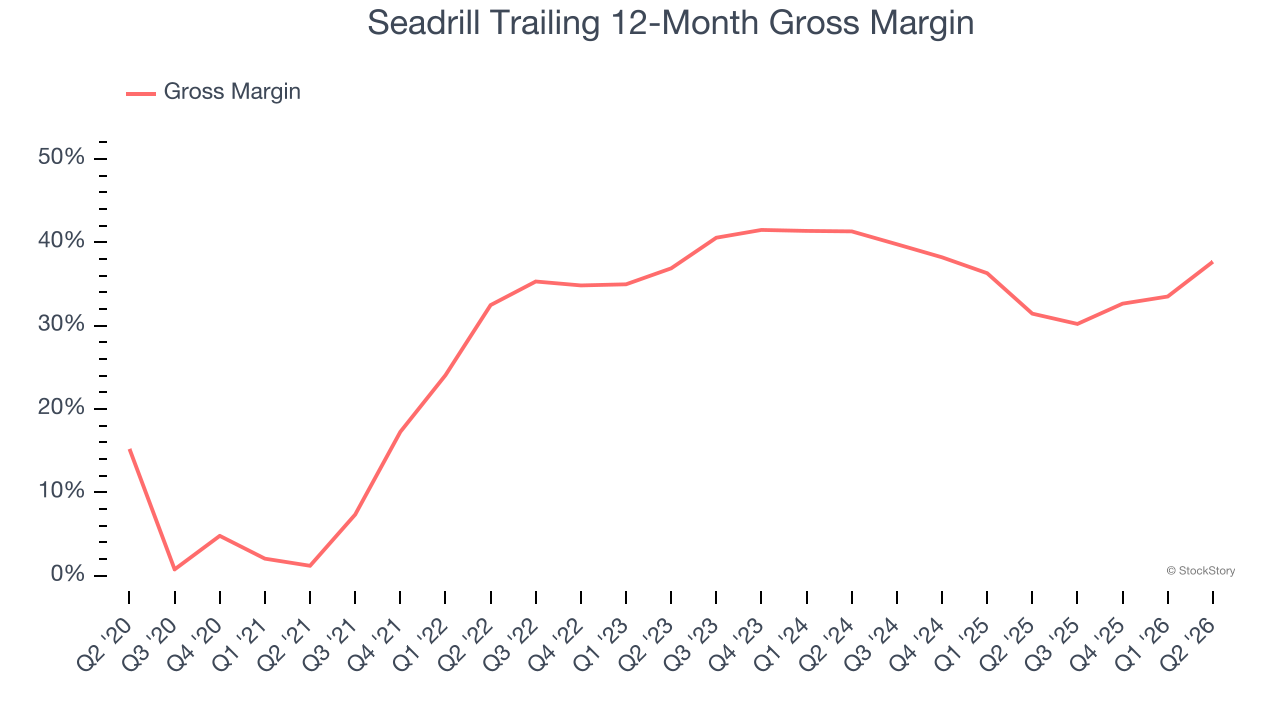
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
Seadrill, which averaged 36.3% gross margin over the last five years, exhibits poor unit economics in the sector. It means the company will struggle more at lower commodity prices than peers with better gross margins.
3. Cash Burn Ignites Concerns
If you’ve followed StockStory for a while, you know we emphasize free cash flow. Why, you ask? We believe that in the end, cash is king, and you can’t use accounting profits to pay the bills.
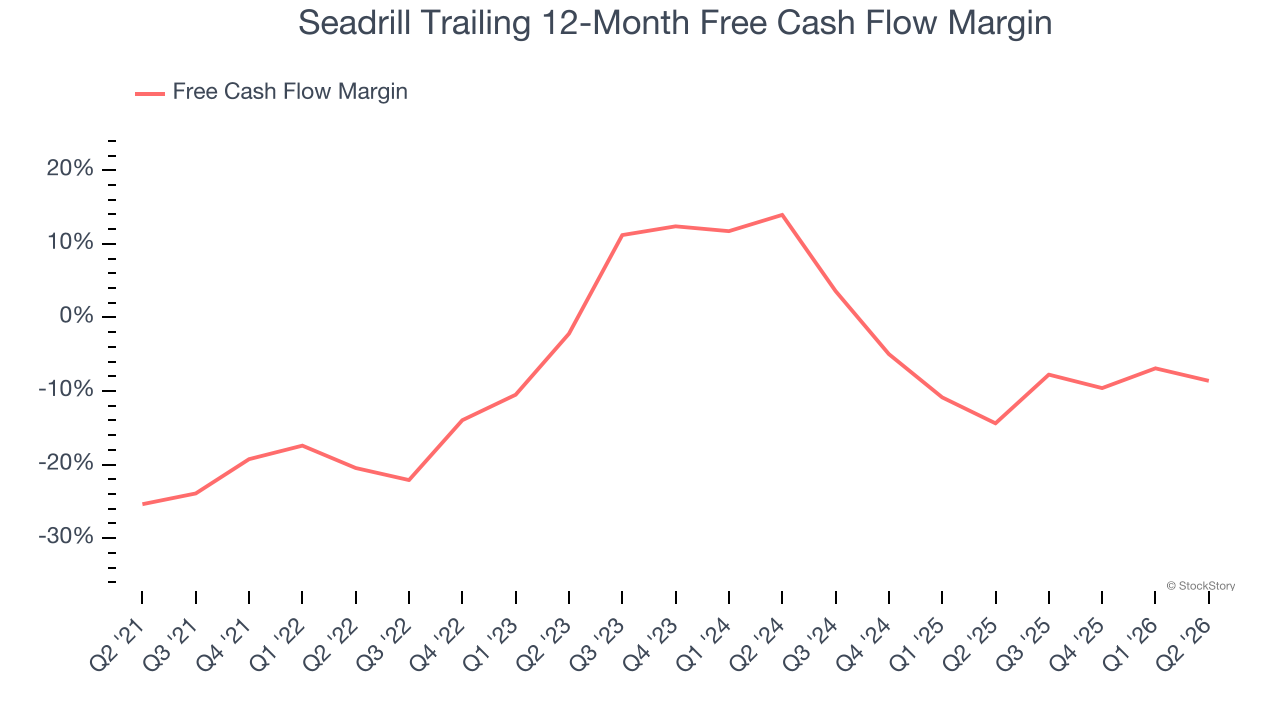
Seadrill’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 5.3%, meaning it lit $5.30 of cash on fire for every $100 in revenue.
Final Judgment
Seadrill falls short of our quality standards. With its shares lagging the market recently, the stock trades at 25.8× forward P/E (or $47.45 per share). This valuation tells us a lot of optimism is priced in - we think other companies feature superior fundamentals at the moment. We’d recommend looking at one of our top digital advertising picks.
Stocks We Would Buy Instead of Seadrill
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.