

EnerSys currently trades at $178.69 per share and has shown little upside over the past six months, posting a middling return of 4.3%. The stock also fell short of the S&P 500’s 16.2% gain during that period.
Does this present a buying opportunity for ENS? Or is its underperformance reflective of its story and business quality? Find out in our full research report, it’s free.
Why Does ENS Stock Spark Debate?
Supplying batteries that power equipment as big as mining rigs, EnerSys (NYSE:ENS) manufactures various kinds of batteries for a range of industries.
Two Things to Like:
1. Outstanding Long-Term EPS Growth
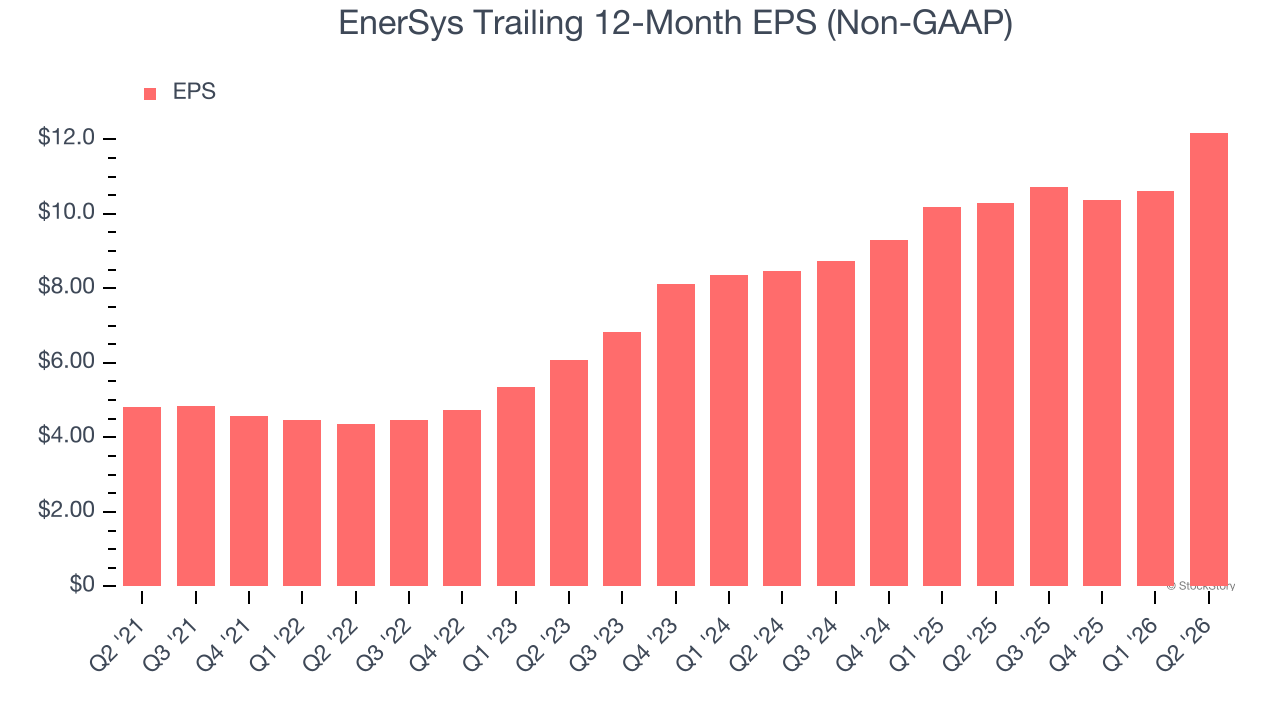
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
EnerSys’s EPS grew at 20.4% compounded annual growth rate over the last five years, higher than its 4.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
2. Increasing Free Cash Flow Margin Juices Financials
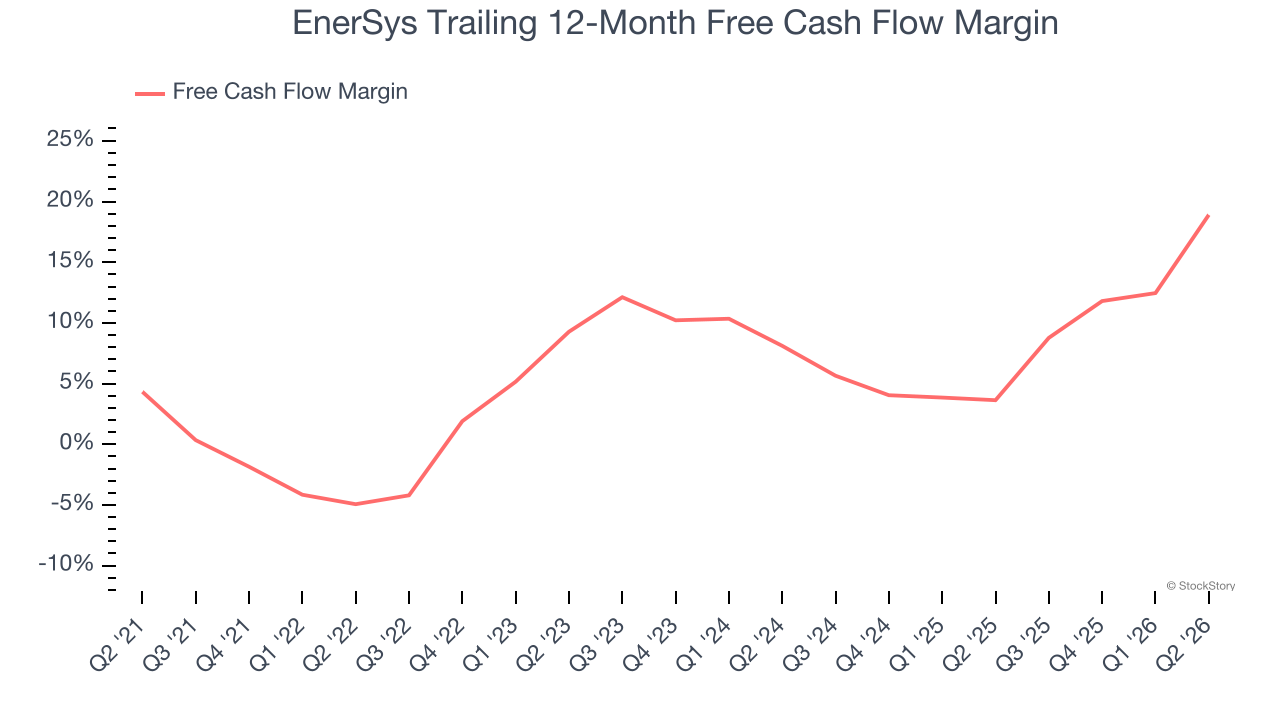
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, EnerSys’s margin expanded by 23.8 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. EnerSys’s free cash flow margin for the trailing 12 months was 18.9%.
One Reason to Be Careful:
Sales Volumes Stall, Demand Waning
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Renewable Energy company because there’s a ceiling to what customers will pay.
Over the last two years, EnerSys failed to grow its units sold. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests EnerSys might have to lower prices or invest in product improvements to accelerate growth, factors that can hinder near-term profitability. 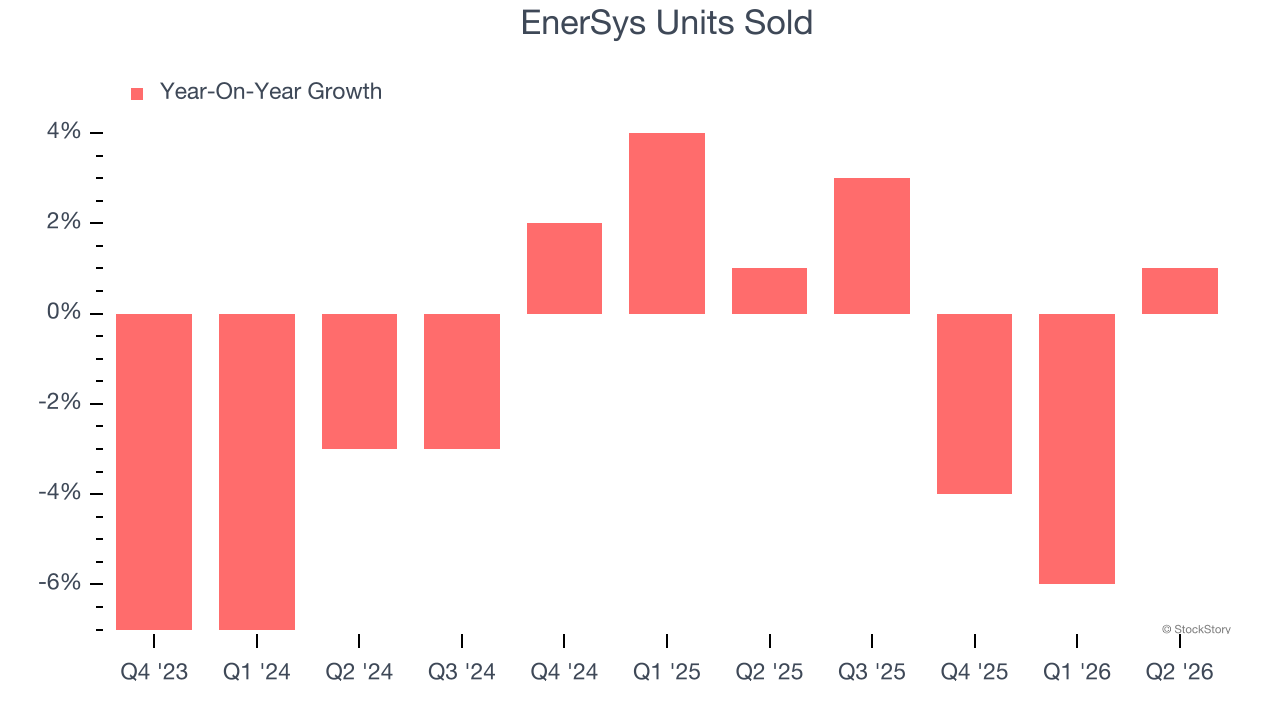
Final Judgment
EnerSys has huge potential even though it has some open questions. With its shares underperforming the market lately, the stock trades at 13.5× forward P/E (or $178.69 per share). Is now a good time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.